A property decision in Fujairah should be built from evidence about the actual asset and the buyer's purpose. A coastal image, an attractive asking price or a general statement about the emirate's development cannot answer whether a specific transaction is appropriate. The purchaser needs to distinguish the property itself, the legal position, the cost of ownership and the assumptions supporting its intended use.
This guide provides an original due-diligence framework rather than a description of eligibility for any particular property. It does not confirm ownership rights, transaction fees, residency entitlement or an investment return. Those questions must be checked for the actual purchaser, property and transaction with the responsible local authority and qualified advisers. Dubai-specific procedures should not be imported into a Fujairah purchase without verifying their relevance.
Begin with the purpose of ownership
Write down what the property is meant to do. A primary home, occasional-use residence, long-term rental investment and property supporting a business can require different assessments. A purchaser who changes purpose midway through a sales conversation may unknowingly change the entire decision model while continuing to rely on the original comparison.
Separate the essential outcome from desirable features. A household may need a practical daily location; an investor may need a sustainable operating model; an occasional user may prioritise maintenance and access when absent. The same unit can fit one purpose and fail another. The first due-diligence task is therefore internal: establish what success means for this purchaser before asking whether the asset can deliver it. An attractive property is not automatically an appropriate commitment.
Make the geography precise
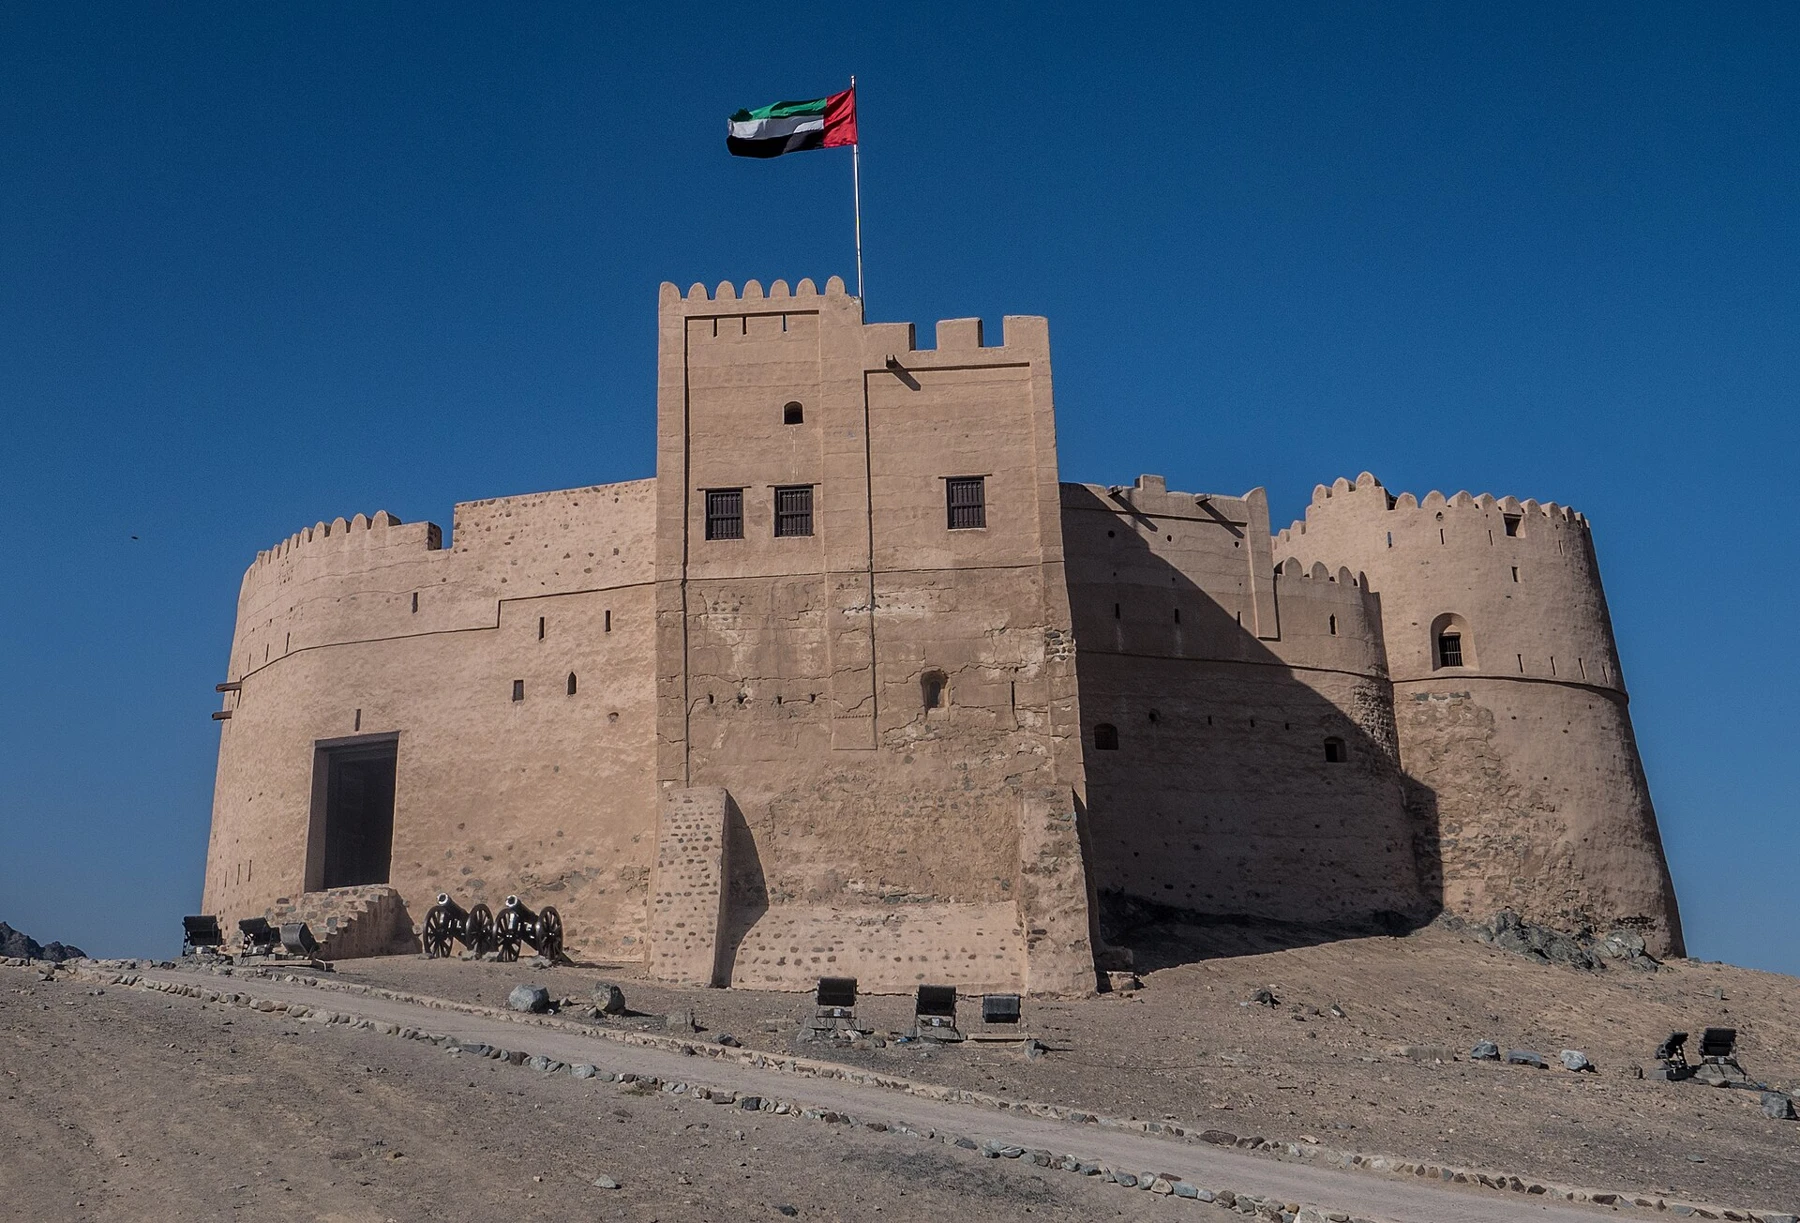
Fujairah's official destination portal distinguishes several places across the emirate, including the city, coastal destinations and mountain areas. [1] Use an exact address and building identity rather than a broad label such as “east coast.” Different locations can support very different daily routines, customer groups and management arrangements.
Map the property against the actual activities relevant to its intended use. For a home, consider work, education, services and household commitments. For a rental investment, investigate the specific audience and the practical conditions under which it would occupy the unit. Do not convert a general tourism description into a demand forecast. Geography is a starting point for research; it becomes commercially meaningful only when connected to the people and transactions the property is supposed to serve.
Establish the legal position before debating yield
Ask the responsible authority and qualified adviser to confirm the purchaser's position, the property's status and the legal route for the intended transaction. Identify the documents that establish title, authority to sell and any material restrictions or encumbrances. A sales representative's confidence is not a substitute for an entity-specific and property-specific assessment.
Keep the legal review separate from the commercial attraction. A unit can appear attractive financially while a material legal question remains unresolved. Conversely, a legally straightforward transaction may still be a poor commercial fit. The purchaser should know which professional is responsible for each assessment and which evidence supports it. No return calculation should be allowed to make an unresolved ownership or authority issue feel less important merely because the projected number looks appealing.
Reconcile the property identity across documents
Create one property identity sheet containing the building, unit reference, location, area description, seller details and intended use. Compare it with the documents and marketing material. If the proposed unit changes, create a new assessment rather than allowing evidence from a similar property to migrate into the decision.
This discipline is useful when a development contains several phases, building types or units with similar photographs. A shared brand does not establish identical condition, obligations or rights. Ask for clarification where a name or reference differs. The objective is a clear chain from the marketed asset to the documents and the proposed payment. A purchaser should be able to explain exactly what is being acquired without relying on a salesperson to reconstruct the story from memory.
Inspect the building as well as the apartment
The unit's interior is only part of what the owner will depend on. Investigate common areas, access, lifts, building services, maintenance arrangements and the process for reporting problems. A qualified inspection may be appropriate for technical questions beyond the purchaser's competence. Cosmetic presentation should not substitute for an assessment of condition.
Ask for available records relevant to the building and ownership responsibilities. Distinguish a problem observed during a visit from a diagnosis that requires a specialist. Record issues precisely and identify who will investigate them. A good inspection does not need to declare every uncertainty catastrophic. It should make the nature, likely consequence and possible cost of unresolved matters easier to understand before a commitment is made.
Understand recurring obligations and management
Request reliable information about the charges and responsibilities that accompany ownership. Identify which costs are regular, which can vary and which may arise from repairs or other events. Ask how the building is managed, who makes relevant decisions and how the owner receives information. Do not assume that a general brochure contains the full operating cost.
For an owner who will be absent, management arrangements deserve particular attention. Who can inspect the unit, coordinate repairs, respond to a tenant and authorise spending? What evidence will the owner receive? A management service is a process with terms and limitations, not merely a percentage in a budget. The purchaser should understand the relationship well enough to know what will happen when something goes wrong, not only how the property will be presented when everything is working.
Build a cash model with explicit assumptions
Start with the acquisition commitment and all applicable transaction-related expenses confirmed for the actual case. Add ongoing costs, financing where relevant, maintenance, management and a reserve for uncertainty. Use current evidence and quotations rather than presenting an illustrative model as an official schedule of fees.
If the property is intended to generate income, show the assumptions for occupancy, rent, collection and costs separately. A model is more useful when a reader can change one assumption and see the effect. Do not describe a result as a return guaranteed by the location or by a developer's reputation. The purpose is to understand the conditions under which the investment works and the amount of cash the owner may need when conditions differ from the preferred forecast.
Investigate demand at the level of the actual unit
A statement that Fujairah attracts visitors or supports commercial activity is not evidence that a particular apartment will achieve a specific rent. Identify the intended tenant or user, the alternatives available and the reasons someone would choose this unit. Investigate the appropriate legal and operational conditions for the proposed use rather than assuming that any rental model can be adopted.
Compare evidence carefully. Asking prices, advertised rents and completed transactions are different kinds of information. A unit's condition, building, location and terms can affect whether a comparison is meaningful. Mark gaps instead of averaging them away. A disciplined purchaser can conclude that more research is needed, that a different unit fits better or that the proposed investment does not meet the required margin of safety. All are legitimate outcomes of due diligence.
Occupancy and tenancy require their own local process
Where the property will be let, investigate the relevant local tenancy and registration arrangements. Fujairah Municipality's Ejaar material provides a local starting point and distinguishes owner, manager and tenant roles. [2] The actual landlord's responsibilities and the requirements of the intended occupancy should be confirmed for the case.
Do not assume that buying the unit completes every step needed to use or let it. A purchaser should understand the sequence from ownership to any relevant permissions, services, management and tenancy documentation. If the business case depends on a particular use, establish that use before committing, not after discovering a restriction. The financial model should follow the lawful operating plan rather than require the legal position to adapt to a preferred spreadsheet.
Consider the cost of changing your mind
Property is a commitment whose exit can involve time, cost and uncertainty. Investigate the applicable transfer, finance and contractual conditions rather than assuming that the owner can sell immediately at the preferred price. An intended short holding period should be tested against a slower or less favourable exit scenario.
Ask what would happen if the household needed to relocate, the investor required cash or the planned tenant did not materialise. The purpose is not to predict a negative outcome. It is to understand the amount of flexibility the purchaser is giving up and whether sufficient financial capacity remains. A property that can be held comfortably under a reasonable stress scenario is a different proposition from one that depends on an early resale to meet the next obligation.
A hypothetical home-versus-investment comparison
Imagine a household considering a unit it would enjoy using occasionally, while also hoping that rental income will cover much of the cost. The household should model personal use and rental operation separately, then examine how they interact. Time reserved for the owner may reduce availability, while a more intensive letting plan may change management needs and wear.
The correct decision might still be to buy, but it should be based on an honest account of both purposes. Do not describe a lifestyle purchase as a purely financial investment to avoid discussing its real cost. Equally, do not allow projected rental income to justify a commitment the household cannot sustain if income is weaker than expected. A clear separation of motives makes the trade-offs more visible and the final choice more defensible.
Evaluate the information providers
Identify who produced each piece of evidence and what interest they have in the transaction. A seller, broker, lender, manager, inspector and legal adviser may each contribute useful information while serving different roles. The purchaser should know whom each professional represents and what their engagement covers.
A polished presentation is not inherently unreliable, but its purpose should be understood. Ask for the underlying document or calculation where a claim matters. A statement that cannot be explained or evidenced should remain provisional. Strong due diligence does not require distrust of everyone involved. It requires clarity about responsibility, incentives and the limits of each source so that one person's marketing claim is not mistakenly treated as another institution's independent confirmation.
Use a property decision table
| Workstream | Core question | Evidence before commitment |
|---|---|---|
| Purpose | What must ownership achieve? | A written purchaser brief |
| Legal position | Can this purchaser undertake this transaction on these terms? | Authority confirmation and qualified advice |
| Identity | Is every document about the same asset? | Reconciled property and party references |
| Condition | What technical or maintenance issues exist? | Appropriate inspection and available records |
| Operating costs | What will ownership require over time? | Current charges, terms and a realistic reserve |
| Demand | Who will use the property and why? | Specific comparable evidence and a lawful operating model |
| Funding and exit | Can the owner carry a less favourable outcome? | Cash timeline and stress scenarios |
The table should reveal unanswered questions rather than produce a decorative score. An unresolved item can be material even if most other rows look favourable. The decision remains incomplete until the purchaser understands how that uncertainty affects the commitment.
The final pre-payment meeting
Before a material transfer or signature, reconcile the asset, parties, legal route, contractual obligations, payment instructions and evidence expected afterwards. Confirm independently any change to payment details. Ask the advisers to identify unresolved matters in plain language and explain the consequence of proceeding with them outstanding.
Then compare the proposed commitment with the original purpose. A long negotiation can gradually change the unit, price or assumptions until the final deal no longer resembles the one initially assessed. The final review should therefore be a fresh decision on the actual transaction, not an automatic conclusion to the effort already invested. Time spent investigating is useful even when it leads to a decision not to buy.
Use a sensitivity review to expose the fragile assumption
Instead of changing every financial input at once, vary one important assumption and examine what it does to the decision. Consider a lower achievable rent, a longer vacancy, a repair cost or a slower exit. The actual figures must come from the purchaser's evidence and circumstances; the method is intended to reveal dependence rather than predict an outcome.
Ask which change would make the commitment uncomfortable. That answer identifies the assumption requiring the strongest verification and the financial reserve that may be needed. A model with a favourable central estimate can still be fragile if a small movement creates a funding problem. Conversely, a modest projected result may be acceptable to a purchaser whose purpose and financial capacity fit it. The decision should reflect the actual owner rather than a universal target return.
Record what the model excludes. Tax treatment, financing changes, transaction expenses or management demands should not disappear merely because they are difficult to estimate. An exclusion is information the decision-maker needs to see. It may require further advice or a wider reserve before the commitment can be assessed responsibly.
Finally, keep lifestyle value separate from financial resilience. A purchaser may rationally value personal use or a particular location, but that preference should not be hidden inside an inflated rental forecast. Honest accounting for the reason to buy makes the choice more coherent. It allows the owner to accept a cost deliberately rather than discover later that an investment narrative was being used to avoid discussing the price of the desired lifestyle.
Frequently asked questions
Can this guide confirm foreign ownership eligibility?
No. Eligibility and property status must be checked for the actual purchaser and asset with the responsible authority and qualified adviser. Do not import another emirate's rules into the assessment.
Does a coastal location establish a rental return?
No. A location can support a research hypothesis, but demand, costs, permitted use and the specific property require evidence. A return model should state its assumptions and test less favourable outcomes.
What is the most important protection against a rushed purchase?
Keep legal, technical and commercial workstreams distinct, maintain a record of unresolved questions and require a final review of the actual transaction before committing money. Attractive numbers should not erase missing evidence.
Official sources and editorial method
Sources checked on 31 October 2026. Official facts are distinguished from CYUAE analysis and clearly labelled hypothetical examples. Confirm current access, eligibility, fees and service requirements with the responsible institution before acting.